


Personal risk insurance : essential but for who and why ?
The november 20, 2024
Today, France is at the forefront of social protection for its population. Whether through the General Social Security Scheme or the various schemes for employees and civil servants, these statuses benefit from reinforced social protection with health insurance on the one hand and the various compulsory mutual insurance companies on the other. But not all professions benefit from the same protection. What about the professions affiliated with Social Security for the self-employed (SSI)?
Whether you're a craftsman, a shopkeeper, a micro-entrepreneur, a self-employed professional, a sole trader, a manager or partner in an SNC or EURL, or a majority shareholder in a SARL, all these professions are covered by Social Security for the self-employed (SSI). So, what's the problem, Jamy?
In principle, these professionals are only partially covered in the event of loss of income due to a life incident. The daily allowances or the disability pension paid only cover part of the loss of income due to the cessation of work. So, it's vital for them to protect themselves and their loved ones. But how can they do this?
Contingency insurance is just the answer! It is an insurance contract designed to provide additional social cover for incidents such as death, incapacity, disability or illness. In other words, it covers temporary or permanent loss of income not covered by your basic insurance.
Here's an illustration of how it works:
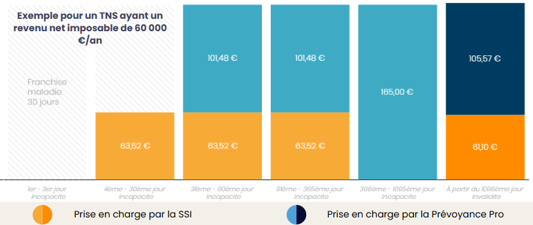
Note that death benefits are also included in the cover offered.
In our example, the self-employed person earns €5,000 per month, giving a daily income of €165. However, his general scheme (SSI) only covers a maximum of 38% of his income. This shortfall may be covered for a short period, but for a longer period it could be dramatic. So, if you want peace of mind, you need to take out cover for the remaining 62%. But how do you select the right cover?
Whether you need to determine the amount of income maintenance protection, the amount of death benefits or the terms and conditions, such as the deductible period or the risks to be insured. Finankap Group, with its 20 years of expertise, is at your disposal to work with you to define the provision adapted to your personal and professional situation to best respond to your concerns.